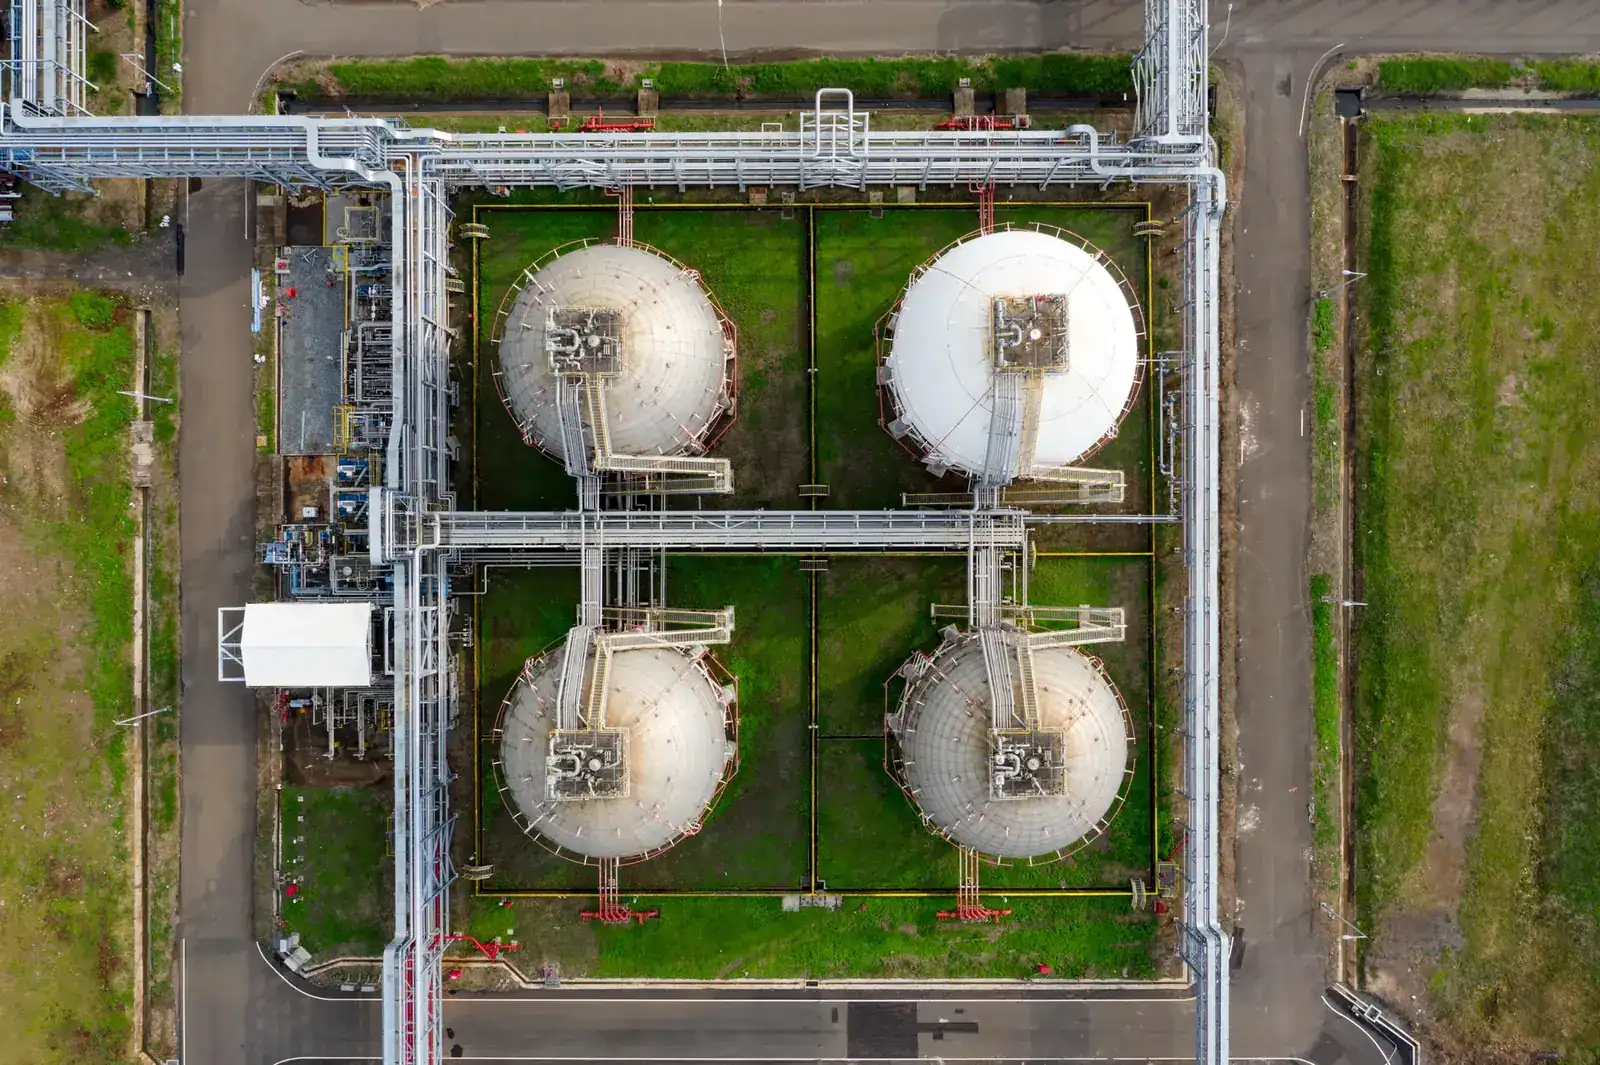
Green hydrogen is made by splitting water into hydrogen and oxygen using electricity from renewable sources such as wind or solar. This process is called electrolysis. It differs from grey hydrogen, made from natural gas with the CO2 released, which National Grid describes as the most common form of production.
Low-emissions hydrogen made up less than 1% of global production in 2024, according to the International Energy Agency (IEA), and it remains more costly than fossil-based hydrogen in the near term. The UK government sees its main role in hard-to-electrify industry, heavy transport, dispatchable power and storage (July 2025); its role in home heating is likely to be limited.
How it works
In electrolysis, an electric current is passed through water, splitting it into hydrogen gas and oxygen. The Environment Agency still classifies electrolysis of water as “an emerging technique” for permitting purposes (2026 update).
The process requires clean water. According to Environment Agency guidance, electrolysis consumes at least 9 kg of pure water for every 1 kg of hydrogen produced. Gross water intake is higher, depending on purification, cooling and recycling.
IRENA describes four main types of electrolyser, each with different maturity and electricity use (figures are 2020 state of the art):
- Alkaline: The most mature technology. It operates at 70–90 °C and used 50–78 kWh of electricity per kg of hydrogen in 2020.
- PEM (proton exchange membrane): Uses platinum and iridium catalysts. It operates at 50–80 °C and used 50–83 kWh/kg in 2020. Higher current density allows smaller stacks.
- AEM (anion exchange membrane): Operates at 40–60 °C and used 57–69 kWh/kg in 2020. It is less mature than alkaline or PEM.
- SOEC (solid oxide): The most efficient on electricity (40–50 kWh/kg in 2020) because some energy comes in as heat, but the least mature, operating at 700–850 °C.
Efficiency is measured against the lower heating value (LHV) of hydrogen, which is 33.3 kWh/kg. A system using about 51 kWh/kg is therefore roughly 65% efficient. IRENA’s 2050 target is 76%, or 43.8 kWh/kg.
Real-world examples
Globally, China dominates. According to the IEA’s Global Hydrogen Review 2025, it holds 65% of global installed electrolyser capacity and nearly 60% of manufacturing capacity. The global pipeline has cooled: announced projects could deliver 37 Mt per year of low-emissions hydrogen by 2030, down from 49 Mt a year earlier, the first decline.
In the UK, Hydrogen Allocation Round 1 (HAR1) selected 11 electrolytic projects in December 2023. These total 125 MW and include Barrow Green Hydrogen, Bradford Low Carbon Hydrogen and Cromarty Hydrogen. By July 2025, the Low Carbon Contracts Company had signed agreements with 10 of the 11 projects.
For heating, the H100 Fife project in Scotland is designed to supply around 300 opted-in homes with green hydrogen from an electrolyser powered by an offshore wind turbine. Construction was under way as of March 2026, according to government guidance. Two hydrogen village plans did not go ahead: Whitby was dropped in July 2023 after local opposition, and Redcar was cancelled in December 2023 when the government said the main source of hydrogen supply would not be available.
What the numbers say
Efficiency and electricity use A 2025 BNEF benchmark, cited by the manufacturer John Cockerill, places Western alkaline systems at about 54.6 kWh/kg and PEM at about 55.1 kWh/kg for full systems.
Costs The IEA says low-emissions hydrogen will remain more expensive than unabated fossil-based production in the near term, with the gap expected to narrow by 2030.
- Electrolysers: In 2024, installed electrolyser costs were USD 2,000–2,600 per kW outside China, compared with USD 600–1,200 per kW for Chinese units installed in China (IEA).
- UK subsidy price: HAR1 projects agreed a weighted average strike price of £241/MWh (£175/MWh in 2012 prices) in December 2023.
- Regional gap: Renewable hydrogen in China is 40–45% cheaper than in Europe or the US, mainly due to cheaper renewable power (IEA, 2025).
Production volume Global hydrogen demand reached almost 100 Mt in 2024, according to the IEA. Demand is still dominated by refining, ammonia, methanol and fossil-based steelmaking.
Limitations and honest assessment
The “colour” confusion Hydrogen is colourless; colours are industry nicknames and there is no universal convention. Grey hydrogen (from natural gas) is the most common. Blue hydrogen adds carbon capture and storage. Pink hydrogen uses nuclear electricity. UK policy does not use colours, preferring “low carbon hydrogen” as defined by the Low Carbon Hydrogen Standard (emissions of 20 gCO2e/MJ or less).
Home heating is uncertain The government’s March 2026 guidance states: “As hydrogen is not yet a proven technology for home heating, a role would come later and likely be limited.” Heat pumps and heat networks remain the primary routes for decarbonising homes.
Where it makes most sense The IEA calls existing uses such as refining “low-hanging fruit”, and sees the fastest technology progress in emerging uses including steel, shipping and aviation.
Storage and transport The Spending Review 2025 confirmed over £500 million for the first regional hydrogen transport and storage network, aiming to be operational from 2031.
Manufacturing concentration China’s electrolyser manufacturing capacity (about 20 GW a year) far exceeded global demand of about 2 GW in 2024, according to the IEA.
The UK angle
Targets and strategy The 2021 Hydrogen Strategy set an aim of 5 GW of low carbon hydrogen production capacity by 2030. The April 2022 British Energy Security Strategy doubled this to up to 10 GW, with “at least half” from electrolytic hydrogen, subject to affordability and value for money. The July 2025 Hydrogen Update to the Market did not restate the 10 GW figure. It said electrification “has moved on rapidly, pointing to a more focused and essential role for hydrogen complementing electrification”, and promised a new hydrogen strategy.
Allocation rounds
- HAR1: 11 projects, 125 MW total. Contracts signed with 10 projects. In July 2025 the government expected all to be operational between 2025 and April 2028.
- HAR2: 27 projects were shortlisted in April 2025, around 765 MW in total according to trade press. In March 2026 the government said it aimed to award contracts in 2026, but no HAR2 contracts had been announced by early October 2026.
- HAR3 and HAR4: The July 2025 update said HAR3 would launch by 2026 and HAR4 from 2028.
Manufacturing investment On 9 April 2026 the government announced £86.5 million to support a 1 GW expansion of ITM Power’s electrolyser factory in South Yorkshire, with over 400 jobs.
Heating policy A strategic decision on hydrogen for heating had been expected in 2026, but none had been published by early October 2026; the government says it “will consult in due course”. The Health and Safety Executive has completed its assessment of the safety evidence for 100% hydrogen heating. The government has also consulted on blending hydrogen into the gas transmission network.
Frequently asked questions
How is green hydrogen made, and how much electricity does it take?
Green hydrogen is made by passing renewable electricity through water to split it into hydrogen and oxygen. In 2020, systems used 50–83 kWh per kg of hydrogen (IRENA). A 2025 BNEF benchmark cited by a manufacturer puts Western systems at around 55 kWh/kg.
What is the difference between green, blue and grey hydrogen?
Grey hydrogen is produced from natural gas and releases CO2. Blue hydrogen is grey hydrogen with carbon capture and storage. Green hydrogen is produced by electrolysis using renewable electricity.
How much of the world’s hydrogen is green today?
In 2024, low-emissions hydrogen accounted for less than 1% of global production (IEA). Most hydrogen is still made from natural gas and coal, mainly for refining, ammonia and methanol.
What is the UK’s hydrogen target and where do the HAR1/HAR2 rounds stand?
The 2022 British Energy Security Strategy set an ambition of up to 10 GW of low carbon hydrogen capacity by 2030; the July 2025 update did not restate it. HAR1 selected 11 projects (125 MW) in December 2023, with contracts signed for 10. HAR2 shortlisted 27 projects in April 2025, but no contracts had been announced by early October 2026.
Will hydrogen replace gas boilers in UK homes?
Unlikely in the near term. The government says any role for hydrogen in home heating “would come later and likely be limited”, with heat pumps and heat networks as the main routes. The Redcar and Whitby village trials were cancelled.
Why is green hydrogen still more expensive than grey hydrogen?
Electricity is the dominant cost of green hydrogen (IRENA, 2020), and electrolysers are expensive to install, although the IEA says the stack itself is only 15–20% of the investment. The IEA expects the gap to narrow by 2030 but to stay larger where gas is cheap.